$$$ KPO and CZM $$$: Net Worth
Showing posts with label Net Worth. Show all posts

Thursday, January 20, 2022

2021 Net Worth

We dabbled in crypto in early 2021 with the plan to allocate just a tiny 1% of our net worth into it. However, I fell deep into the rabbit hole, discovered LUNA/Terra and eventually persuaded/convinced CZM to screw/ignore the 1% allocation. lol. Now it is taking up close to 50% of our net worth.
Our WhatsApp group chat

In addition, I started exploring DeFi with my friends (some of you can probably tell why it was named that way. Hint: BSC. lol) and eventually we started a crypto business with just US$3k capital. It is currently generating conservatively a few thousand dollars of passive income monthly (probably not that passive for my friends because they are doing the heavy lifting/coding. lol). It is a crazy amount for us because this was achieved in months as compared to our dividends portfolio which we spent years building.

Besides crypto, another factor that contributed to the growth of our wealth is the use of leverage.

Debt/leverage breakdown:
Stocks - SG$271,199
Crypto - US$75,269 (~SG$101,433)
House - SG$350,538

Total: ~SG$723,170

I believe the amount of debt we have taken might make some of you sleepless but it isn't really that much. If you think about it, anyone buying a private property without investing would have taken on much more debt but grow their wealth much slower (just my opinion). Anyway, we borrowed ~SG$372k to invest and it has exceeded our mortgage of ~SG$350k. Once again, leverage isn't for everyone and most importantly, never put yourself in a position where there is a high chance of being liquidated/margin call.

Let me introduce the concept of net worth and its importance once again for the new readers.

Net worth can be calculated by taking all the assets and subtracting away all the debts/liabilities. This is the classic comic where everyone is actually poorer than the beggar who has a net worth of $2.73. Your friends/colleagues may be living in a huge condominium, driving some fancy car but it could all be financed by debts. There is absolutely nothing wrong with that as long as their income allows so but anything can happen! Do not be the The "Poor" Pilot With Multiple Properties. You can refer to the following article on the importance of net worth by InvestmentMoats - Don’t Track Your Expenses or Budget First. Plot Your Net Worth Instead. 

Cash
This is all the money we have in our savings accounts. Regular readers will know we are investing aggressively that we hardly keep/hold onto cash. No emergency fund as well which I do not recommend since it is personal finance 101. We felt that there's no need for it at the moment, will probably work start saving when CZM retires?

Our Cash: ~ $25,000

CPF
Every month, I will try to show CZM her net worth in order to motivate her to work harder towards financial freedom. However, she would always say I inflate her net worth because I included CPF. lol. I am sure some of you may have the same mentality but like I always tell her, CPF is our money and should be included as our retirement planning.

Our CPF: ~ $380,000 (OA + SA + MA)

Investment - Stocks/TradFi
The return through the use of leverage is not being captured and should be higher. Anyway, our overall time-weighted return is 18.01% and XIRR is 6.99%. The majority of our portfolio is tracked using StocksCafe except for Endowus which is about 35k and we have about 271k of leverage/debt. You can refer to Portfolio - December 2021 for the detailed breakdown.

The screenshot was taken after 2021 so numbers will not tally

If you are interested in the smart portfolio tracker (StocksCafe) which I am using as shown above, sign up using my link for a longer trial period :) Refer to our Referrals page for more information.

Our Investment: ~$756,000

Investment - Crypto/DeFi


The majority of our crypto investments are in Terra. You can refer to Portfolio - December 2021 for the detailed breakdown.

What's excluded:
- Crypto Business


I minted/purchased our first NFTs last year September. It costs about 3 LUNA or US$123 then. I sold one for 118 LUNA (~US$4,838 then or ~US$9k now) and kept the remaining 2. One of them (#10902) has a silver crown with a floor price of 250 LUNA or ~US$20k and the other (#9868) is a top 5% glitch punk. Both of them are much rarer than what the floor is trading at but conservatively, they could be sold/valued at a minimum of ~US$40k in total. Of course, the most conservative valuation is 0 which is why they were excluded :)

Our Investment: ~$1,073,000

Property
I believe that property should be included in the computation of net worth. If one excludes the value of the property, the money (cash/CPF) you use to pay for the loan/mortgage will be no different as disappearing into the thin air or throwing it into the sea. Hence, I will be valuing the property based on the total payment (interest + renovation cost) till date. This ensures that our money will not "disappear" and act as a floor/minimum amount (total payment + remaining loan + markup/profit) to sell in the future.

I can imagine people selling their house at market value + markup, thinking that they made money from the sale but it is totally possible that market price + markup < total payment + remaining loan. Does this make sense or is it too confusing? lol.

Anyway, the cost of our HDB + the payment made so far is ~520k and the current outstanding loan is 351k.

Our Property: ~$168,000

Total
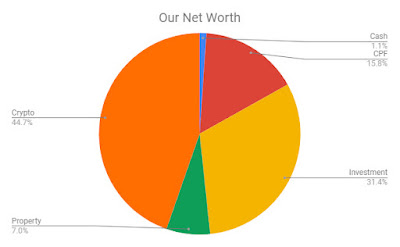

Our Net Worth: ~$2,404,000

Here you go! Our net worth pie chart, it looks pretty yummy to me :) 


Oh, we also have about 465k miles which are just as valuable/useful as our NFTs at the moment and are valued at 0 dollars as well. lol.

Are you tracking your net worth?


On a side note, Futu's moomoo app free AAPL share sign-up promotion is back for this month. Do read the T&C here for more information. If you have yet to open an account, you can do so using our referral link :)

Accidentally clicked on the annoying ads? Let me thank you in advance as you are indirectly doing good as we will be Donating 100% Ads Revenue Going Forward!

You might be interested in these blog posts too:
- 2017 Net Worth: ~$510,000
- 2018 Net Worth: ~$640,000
- 2019 Net Worth: ~$886,000
- 2020 Net Worth: ~$1,107,000
- 2021 Net Worth: ~$2,404,000

Do like any of the following for the latest update/post!
1. FB Page - KPO and CZM
2. Twitter - KPO and CZM
3. Click here to subscribe using email :)
4. Instagram - KPO_and_CZM (Did you see those delicious food photos to the right --> Unfortunately, you can't see it on mobile.)

Sunday, January 3, 2021

2020 Net Worth

Let me start by wishing everyone a Happy New Year! 2020 has been an incredible year for us and manage to achieve/do most of what we had planned to do. You can take a look at last year update here - 2019 Net Worth. We took 1 month off from work and did a RTW trip to Mexico, Peru, Bolivia, Brazil, and Switzerland in February before COVID got really bad/serious. Unfortunately, travelling to Hokkaido and Scandinavia/Northern Europe with our family did not happen. I got my promotion and change job after a few months resulting in a double bump in salary. Recession sort of happened but our portfolio still manages to hit more than half a million with a V-shaped recovery. The best thing that happened to us is the addition to our family - Baby Ong!


I do not think leisure travel is going to resume anytime soon and with a baby, we are definitely not planning to travel, hence no grand travel plan although we have about half a million miles now @_@" As a parent, our mentality has changed, it is no longer about ourselves and it's always about the baby. Anyway, this is what we hope to achieve for year 2021:
1. Baby Ong grows up healthily since health is wealth!
2. We are still on track to a 1 million portfolio by age 34. It is currently at 613k without leverage and 669k with leverage and the target for this year is 720k without leverage. 
3. Given the low interest environment, we are looking to increase the use of leverage "safely" and hopefully be able to accelerate the growth of our portfolio. I first blogged/explored the possibility of using it in 2018 (Leverage - A Double-Edged Sword) but only took the plunge and used it last year and it has been working well for us so far. Shall blog about it separately next time.

Our net worth update is an annual event but I blogged about it a few months back when we reached a milestone - 1 Million Combined Net Worth By Age 30.

Let me introduce the concept of net worth and its importance once again for the new readers.

Net worth can be calculated by taking all the assets and subtracting away all the debts/liabilities. This is the classic comic where everyone is actually poorer than the beggar who has a net worth of $2.73. Your friends/colleagues may be living in a huge condominium, driving some fancy car but it could all be financed by debts. There is absolutely nothing wrong with that as long as their income allows so but anything can happen! Do not be the The "Poor" Pilot With Multiple Properties. You can refer to the following article on the importance of net worth by InvestmentMoats - Don’t Track Your Expenses or Budget First. Plot Your Net Worth Instead. 

Cash
This is all the money we have in our savings accounts. Regular readers will know we are investing aggressively that we hardly keep/hold onto cash. No emergency fund as well which I do not recommend since it is personal finance 101. We felt that there's no need for it at the moment, will probably work start saving when we get older.

Our Cash: ~ $22,000

CPF
Every month, I will try to show CZM her net worth in order to motivate her to work harder towards financial freedom. However, she would always say I inflate her net worth because I included CPF. lol. I am sure some of you may have the same mentality but like I always tell her, CPF is our money and should be included as our retirement planning.

Our CPF: ~ $322,000 (OA + SA + MA)

Investment
I have yet to blog about our portfolio performance and although we outperformed STI for this year, the portfolio underperformed when compared against SPY and IWDA. Having said that, the return through the use of leverage is not being captured and should be higher. Anyway, our overall time-weighted return is 5.82% and XIRR is 5.33%.


If you are interested in the smart portfolio tracker (StocksCafe) which I am using as shown above, sign up using my link for a longer trial period :) Refer to our Referrals page for more information.


Majority of our portfolio are tracked using StocksCafe except for Endowus which is about 12k and we have about 56k of leverage/debt.

Our Investment: ~$613,000

Property
I believe that property should be included in the computation of net worth. If one excludes the value of the property, the money (cash/CPF) you use to pay for the loan/mortgage will be no different as disappearing into the thin air or throwing it into the sea. Hence, I will be valuing the property based on the total payment (interest + renovation cost) till date. This ensures that our money will not "disappear" and act as a floor/minimum amount (total payment + remaining loan + markup/profit) to sell in the future.

I can imagine people selling their house at market value + markup, thinking that they made money from the sale but it is totally possible that market price + markup < total payment + remaining loan. Does this make sense or is it too confusing? lol.

Anyway, the cost of our HDB + the payment made so far is ~514k and the current outstanding loan is 364k.

Our Property: ~$150,000

Total


Our Net Worth: ~$1,107,000

Here you go! Our net worth pie chart, it looks pretty yummy to me :) 

We have also clocked >1,000,000 page views! Thank you very much to all our readers!

Alright, I digress too much. Are you tracking your net worth?

You might be interested in these blog posts too:
- 2017 Net Worth: ~$510,000
- 2018 Net Worth: ~$640,000
- 2019 Net Worth: ~$886,000
- 2020 Net Worth: ~$1,107,000

Do like any of the following for the latest update/post!
1. FB Page - KPO and CZM
2. Twitter - KPO and CZM
3. Click here to subscribe using email :)
4. Instagram - KPO_and_CZM (Did you see those delicious food photos to the right --> Unfortunately, you can't see it on mobile.)

Thursday, November 19, 2020

1 Million Combined Net Worth By Age 30

We have achieved another one of our goals - $1,000,000 net worth by age 30! We ended 2019 with a net worth of ~$886,000 and was hoping to achieve the goal this year. When covid happened and the stock market crashed in March, I told CZM that it's not happening this year since the majority of our wealth is in the market. Surprise surprise, the market has recovered even before the pandemic is over (technically the vaccine isn't out yet, the economy is still bad and we still can't travel).

Let me introduce the concept of net worth and its importance once again for the new readers.

Net worth can be calculated by taking all the assets and subtracting away all the debts/liabilities. This is the classic comic where everyone is actually poorer than the beggar who has a net worth of $2.73. Your friends/colleagues may be living in a huge condominium, driving some fancy car but it could all be financed by debts. There is absolutely nothing wrong with that as long as their income allows so but anything can happen! Do not be the The "Poor" Pilot With Multiple Properties. You can refer to the following article on the importance of net worth by InvestmentMoats - Don’t Track Your Expenses or Budget First. Plot Your Net Worth Instead. 

In our previous net worth update, I simply share the numbers but since this is a special occasion, shall share some screenshot too :)

Cash
This is all the money we have in our savings accounts.

KPO DBS Accounts

CZM DBS Accounts

I have blogged about how we used the Multiplier as our main savings account and the use of a joint account to achieve higher interest previously. The last/latest article can be found here - DBS Multiplier Upcoming Changes. 

KPO UOB Account

The UOB account was created when we refinance our HDB housing loan/mortgage to UOB. I usually keep this around $1k to avoid the fall below fee and it just went below $1k after the giro deduction for my credit card bills. I also have multiple SCB accounts that have $0 balance (no fall below fee for priority customer) which I will show later for a different reason.

Regular readers will know we are investing aggressively that we hardly keep/hold onto cash. No emergency fund as well which I do not recommend since it is personal finance 101. We felt that there's no need for it at the moment, will probably work start saving when we get older.

Our Cash: ~$16,000

CPF
Every month, I will try to show CZM her net worth in order to motivate her to work harder towards financial freedom. However, she would always say I inflate her net worth because I included CPF. lol. I am sure some of you may have the same mentality but like I always tell her, CPF is our money and should be included as part of our retirement planning.

KPO CPF

CZM CPF

At the start of our career and before we got our BTO, we transferred everything in OA to SA to take advantage of the higher interest in SA. However, the plan now is to leave more money in OA to act as a buffer for our mortgage. As of now, we can become jobless for ~3.6 years without worrying about the mortgage. Another reason why I stopped transferring to SA is for tax optimization purposes. The option to top up SA up to $7k yearly will disappear once FRS is met. You can how I reduce our taxes by performing Voluntary Contribution (VC) to CPF Medisave and RSTU (Retirement Sum Topping-Up to SA).

Our CPF: ~$308,000 (OA + SA + MA) 

Investment
Our portfolio has grown to >$600,000 (another record high!) after the news of the vaccine came out and since our last update (Portfolio - October 2020 - $567,374).

All our investments are tracked using StocksCafe (including StashAway and Syfe) except for the Endowus portfolio.


Hence, our total portfolio is ~$625,000 currently (including leverage).


The only 2 stocks in my CDP were from an IPO (Just Another Netlink Trust IPO Analysis) and the one time when DBS/Vickers thought I was an accredited investor and offered a private placement (Keppel DC REIT Private Placement). Probably applied too little and the banker found it suspicious. Stopped receiving all those HDB bonds/private placement emails shortly. Oh well.


The majority of our investments are with SCB in 2 different accounts and one of them is a lien account where I pledge shares in order to borrow money from the bank at a lower interest. You can read more about it here - Leverage - A Double-Edged Sword.


The account highlighted in yellow is the leverage/amount I am borrowing from the bank to invest. $15k Euro was used to invest in Cromwell European REITs. Although you see $51k, $20k were used on Singlife for 2.5% interest (ignore it since I did not include it in the cash section) and $31k were invested - Biggest Losses in a Day + Start of Leverage.

Total Leverage: ~$56,000

Our Investment: ~$569,000

Property
I believe that property should be included in the computation of net worth. If one excludes the value of the property, the money (cash/CPF) you use to pay for the loan/mortgage will be no different as disappearing into the thin air or throwing it into the sea. Hence, I will be valuing the property based on the total payment (interest + renovation cost) till date. This ensures that our money will not "disappear" and act as a floor/minimum amount (total payment + remaining loan + markup/profit) to sell in the future.

I can imagine people selling their house at market value + markup, thinking that they made money from the sale but it is totally possible that market price + markup < total payment + remaining loan. Does this make sense or is it too confusing? lol.


Property value based on total payment (including interest + renovation cost): ~$514,000


Valuing at cost + total payment is pretty conservative as the market valuation is ~$635,000!


Our Housing Loan: $365,000

Our Property: ~$149,000

Total


Our Net Worth: ~$1,042,000

The question is how to achieve something similar? Honestly, there's no get rich quick scheme. In my opinion, it always boils down to the followings:

1. Work hard to increase your salary/career/business

Unfortunately, this will always be your main source of income, not from dropshipping or owning multiple properties. I have blogged about this previously - >100% "Return" on Salary and your salary growth should not be linear especially at the early stage of your career. If you are below median income, work towards it. After that work towards getting $6k for maximum CPF contribution rate and towards the next tax bracket and so on. Work for your promotion, if there's no growth or you are getting too comfortable, change a company. The best way to differentiate yourself is to learn programming and automate some manual tasks e.g. Python to automate the boring stuff.

2. High Savings Rate

Our savings rate is around 60-70%. Ignore the last 3 months as I have not tabulated our expenses and they are after deducting those fixed expenses only (e.g. housing loan, parents' allowance, insurance, etc.). To do that, cut down on your expenses. Determine what are your needs (e.g. food) and wants (e.g. new shirt/bag). In addition, we made a decision that we will not get a car (even after Baby Ong is born).

Anyway, multiple bloggers have blogged about this previously. One of the more popular ones would be from Mr. Money Mustache - The Shockingly Simple Math Behind Early Retirement. If you are only saving 10% and leading a YOLO life, good luck to you!

3. Invest and do not time the market

We continued to invest regardless of the market movement. We have a monthly investment plan through StashAway, Syfe, and Endowus and we stick to it. If you are constantly holding on to cash waiting for the next big crash that may/may not happen, you are losing money - the opportunity cost to invest and grow your money. 

In the past, to invest/DCA, one will have to either purchase ILP or do it through a unit trust/fund sold by the banks. All these have a very high cost/expense ratio. However, with the various robo-advisors currently in the market, there is really no excuse not to invest your money when they make it so hassle-free and cost-effective. In addition, remember that you are investing for the long term, there's no need to think about selling/withdrawing them when you see a little profit. Sharing this old article again - Never Ever Buy Investment-Linked Policy (ILP). 

At the end of the day, everyone's journey towards financial freedom is different. Let's work hard towards them! Start by tracking your net worth :)

You might be interested in these blog posts too:
- 2017 Net Worth: ~$510,000
- 2018 Net Worth: ~$640,000
- 2019 Net Worth: ~$886,000

Do like any of the following for the latest update/post!
1. FB Page - KPO and CZM
2. Twitter - KPO and CZM
3. Click here to subscribe using email :)
4. Instagram - KPO_and_CZM (Did you see those delicious food photos to the right --> Unfortunately, you can't see it on mobile.)

Thursday, January 2, 2020

2019 Net Worth

Let me start by wishing everyone a happy 2020 again! This was supposed to be my first post for the year but the move by DBS stole the limelight - DBS Multiplier Account Changes For The Worst.


This year will be an exciting year with many many things to look forward to!
1. This is our first year staying together as husband and wife in our new home for a full year. Expenses are definitely going to increase but we will be able to forecast more accurately as a family.
2. We will be doing our RTW trip going to Mexico, Peru, Bolivia, Brazil, and Switzerland next month!
3. Bringing CZM's family to Hokkaido on Business flights using Alaska miles (the hack is no longer available).
4. Going to the Scandinavia/Northern Europe (Denmark, Norway, Sweden, Finland and Estonia) with my family
5. I should be getting my promotion which means an increase in salary!
6. Our portfolio should reach half a million according to our forecast and IF recession doesn't happen this year. lol.

Alright. Let me just share the same importance of tracking net worth once again for the new readers.


This is the classic comic where everyone is actually poorer than the beggar who has a net asset of $2.73. Your friend/colleague may be living in a huge condominium, driving some fancy car but it could all be financed by debts. There is absolutely nothing wrong with that as long as their income allows so. You can refer to the following articles/google on the importance of net worth.

InvestmentMoats - Don’t Track Your Expenses or Budget First. Plot Your Net Worth Instead

Cash
This is all the money we have in our savings accounts. Our cash dropped as compared to last year because we just completed our renovation few weeks back. You can read about the total cost here - Renovation Cost for Our New House. In addition, I also did a Voluntary Contribution (VC) to CPF Medisave for Tax Reduction.

Our Cash: ~ $22,000 (-54.2%)

CPF
Every month, I will try to show CZM her net worth in order to motivate her to work harder towards financial freedom. However, she would always say I inflate her net worth because I included CPF. lol. I am sure some of you may have the same mentality but like I always tell her, CPF is our money and should be included as our retirement planning.

Our CPF: ~ $262,000 (OA + SA + MA) (+19.6%)

Investment
I have yet to blog about our portfolio performance (still in draft mode!) but I am proud to say that we have outperformed the index (STI). Overall, our time-weighted return is 19.54% and XIRR is 6.99%.


I have also invested some of my SRS money ($3,500) with Endowus since my last review. Will blog more about Endowus in the future.


Our Investment: ~$469,000 (+33.2%)

Property
HUGE change as compared to last year. We took a 25 years HDB loan for our 4 room BTO and started paying for the loan mid last year.

I believe that property should be included in the computation of net worth. If one excludes the value of the property, the money (cash/CPF) you use to pay for the loan/mortgage will be no different as disappearing into the thin air or throwing it into the sea. Hence, I will be valuing the property based on the total payment (interest + renovation cost) till date. This ensures that our money will not "disappear" and act as a floor/minimum amount (total payment + remaining loan + markup/profit) to sell in the future.

I can imagine people selling their house at market value + markup, thinking that they made money from the sale but it is totally possible that market price + markup < total payment + remaining loan. Does this make sense or is it too confusing? lol.


Our Property: ~$133,000 (+533.2%)

Total


Our Net Worth: ~$886,000 (+38.4%)

Here you go! Our net worth pie chart, it looks pretty yummy to me :) We are so close to becoming a millionaire in net worth before the age of 30! Hopefully, it happens before both of us turn 30 this year. Hahaha. On a side note, we are already a millionaire in KrisFlyer miles @_@"


We also have ~11k Asia Miles and ~55k Alaska Miles in each of our accounts thanks to the Cathay error fare.

We have also clocked 1,000,000 page views! Thank you very much to all our readers!

Alright, I digress too much. Are you tracking your net worth?

You might be interested in these blog posts too:
- 2017 Net Worth: ~$510,000
- 2018 Net Worth: ~$640,000
- 2019 Net Worth: ~$886,000

Do like any of the following for the latest update/post!
1. FB Page - KPO and CZM
2. Twitter - KPO and CZM
3. Click here to subscribe using email :)
4. Instagram - KPO_and_CZM (Did you see those delicious food photos to the right --> Unfortunately, you can't see it on mobile.)

Monday, December 31, 2018

2018 Net Worth

Let me start by wishing everyone a happy 2019!


Time flies! Another year has passed in a blink of an eye, did you manage to achieve your 2018 new year resolutions? If not, it is ok (I have been trying to lose weight every single year and finally did it this year. Hahaha), just set new resolutions today and work towards them starting tomorrow!

Net worth is easily one of the most important financial numbers one should know. It is like your personal balance sheet.


This is the classic comic where everyone is actually poorer than the beggar who has a net asset of $2.73. Your friend/colleague may be living in a huge condominium, driving some fancy car but it could all be financed by debts. There is absolutely nothing wrong with that as long as their income allows so. You can refer to the following articles/google on the importance of net worth.

InvestmentMoats - Don’t Track Your Expenses or Budget First. Plot Your Net Worth Instead

Cash
This is all the money we have in our savings accounts. You can read how we maximize the interest we are getting from our savings accounts here - DBS Multiplier + SSBs + Joint Account = Higher Interest! We are starting to build up our cash holdings for multiple reasons - our BTO house will be ready next year and we probably need a large sum of money for renovation. As you know, the market has been pretty volatile and hopefully, when it really crashes, we will have some cash to buy cheap :)

Our Cash: ~ $48,000

CPF
Every month, I will try to show CZM her net worth in order to motivate her to work harder towards financial freedom. However, she would always say I inflate her net worth because I included CPF. lol. I am sure some of you may have the same mentality but like I always tell her, CPF is our money and should be included as our retirement planning.

I am pretty excited to see the interest (estimated ~$7,000+) which will be credited soon!

Our CPF: ~ $219,000 (OA + SA + MA)

Investment
I have yet to blog about our portfolio performance (still in draft mode!) but it definitely underperformed the index :( Overall, we are still on the positive side (+0.18%) as of 28/12/2018. Not so positive if we were to look at the time-weighted return of -1.99%.


Our Investment: ~$352,000

Property
No change as compared to last year.

I believe that property should be included in the computation of net worth. If one excludes the value of the property, the money (cash/CPF) you use to pay for the loan/mortgage will be no different as disappearing into the thin air or throwing it into the sea. However, I would be conservative by valuing the property at cost/purchase price.


We have only paid the first 5% downpayment so far and yet to start paying for the housing loan (still building). So I will just assume that the remaining $402,420 will be financed by the housing loan/mortgage. That would mean the value of our property is purchase price ($423,600) - loan ($402,420) = $21,180. If you are wondering, it is a 4 room HDB at a matured estate. What is the probability of us being your future neighbour? lol.

Our Property: ~$21,000

Total


Our Net Worth: ~$640,000

Here you go! Our net worth pie chart, it looks pretty yummy to me :) CZM was asking if it is possible to hit $1 million by age 30... Shall try to estimate and forecast it another day.

Are you tracking your net worth?

You might be interested in these blog posts too:
- 2017 Net Worth

Do like any of the following for the latest update/post!
1. FB Page - KPO and CZM
2. Twitter - KPO and CZM
3. Click here to subscribe using email :)
4. Instagram - KPO_and_CZM (Did you see those delicious food photos to the right --> Unfortunately, you can't see it on mobile.)

Sunday, December 24, 2017

2017 Net Worth

Let me start by wishing everyone Merry Christmas!!!

Net worth is easily one of the most important financial numbers one should know. It is like your personal balance sheet.


This is the classic comic where everyone is actually poorer than the beggar who has a net asset of $2.73. Your friend/colleague may be living in a huge condominium, driving some fancy car but it could all be financed by debts. There is absolutely nothing wrong with that as long as their income allows so. You can refer to the following articles/google on the importance of net worth.

InvestmentMoats - Don’t Track Your Expenses or Budget First. Plot Your Net Worth Instead
Cash
This is all the money we have in our savings accounts. We are in the midst of transferring our salary crediting account to DBS Multiplier Account because we go wherever there is higher interest! Bye OCBC 360! Shall not reveal the actual amount we have but all of them will be eligible for the higher interest and you can probably try to guess from the pie chart below :)

Our Cash: > $30,000

CPF
Every month, I will try to show CZM her net worth in order to motivate her to work harder towards financial freedom. However, she would always say I inflate her net worth because I included CPF. lol. I am sure some of you may have the same mentality but like I always tell her, whatever that is in CPF is our money and its main purpose is for retirement, not housing.

Screenshot is taken from 2017_MMGPI_Report.pdf 
Singapore has one of the best pension/retirement system in the "world" (ranked number 7 out of 30 countries and number 1 in Asia) according to the 2017 Melbourne Mercer Global Pension Index. I find it extremely amusing when my colleagues from other parts of the world are envious of our retirement system while the locals are complaining so much about it. One of the biggest complain I always hear is the need to repay the "lost" interest when one sells the house but I shall not digress further. lol.

You can refer to these articles for more information:
- Straits Times: Singapore has best pension system in Asia: Mercer index
- globalpensionindex.com: 2017 Melbourne Mercer Global Pension Index

Our CPF: > $100,000 (OA + SA + MA)

Investment
I blogged about our portfolio last week. You can read in detail here - Portfolio Performance in 2017. We have achieved pretty decent return this year (XIRR of 14.85%) and across all years (XIRR of 9.60%).

We have also invested some money through StashAway and the time-weighted return has been decent at 3.5% (SGD) and 5.3% (USD) till date. USD is giving higher return because there is some FX loss when converting the investment back to SGD.


Our Investment: $295,000

Property
I believe that property should be included in the computation of net worth. If one excludes the value of the property, the money (cash/CPF) you use to pay for the loan/mortgage will be no different as disappearing into the thin air or throwing it into the sea. However, I would be conservative by valuing the property at cost/purchase price.


We have only paid the first 5% downpayment so far and yet to start paying for the housing loan (still building). So I will just assume that the remaining $402,420 will be financed by the housing loan/mortgage. That would mean the value of our property is purchase price ($423,600) - loan ($402,420) = $21,180. If you are wondering, it is a 4 room HDB at a matured estate. What is the probability of us being your future neighbour? lol.

Our Property: $21,180

Total

Our Net Worth: $510,000

Here you go! Our net worth pie chart, it looks pretty yummy to me :) CZM was asking if it is possible to hit $1 million by age 30... Shall try to estimate and forecast it another day.

Are you tracking your net worth?

Do like any of the following for the latest update/post!
1. FB Page - KPO and CZM
2. Twitter - KPO and CZM
3. Click here to subscribe using email :)
4. Instagram - KPO_and_CZM (Did you see those delicious food photos to the right --> Unfortunately, you can't see it on mobile.)