Our portfolio grew by 6.76% to $286,449 - $8,217.65 of capital injection and around $9,925.66 of capital growth! I got to say the whole of October has been a really good month for property, construction and REIT stocks which form majority of our portfolio :)

There is a lot of activities this month!
SOLD
- Saizen REIT (8,900 units) @ $0.03223 (Delisted - P&L: $3,184.64)
- Sing Holdings (4,400 units) @ $0.47 (P&L: $321.04)
- Wee Hur (5,000 units) @ $0.285 (P&L: -$313.21)
- Croesus Retail Trust (6,801 units) @ $1.17 (Delisted - P&L: $3,339.89)

Saizen REIT was one of our first investment in REIT and we have been holding on to it for about 3 years. I was hoping the reverse takeover would happen but it did not. The huge loss in P&L is because when it got bought over, it distributed its capital in the form of dividends last year. Overall, we made an absolute +39.9% from it and an annualized return of +12.4%.

I was just blogging about Sing Holdings last month that it should trade nearer to its peers PB and it came faster than I expected! It was sold as the trailing stop loss I set got triggered. Fortunately, the price was near what I had in mind and there was a better opportunity (Singtel). Overall, we made an absolute +18.4% and an annualized return of +514.6% for holding 34 days. lol.

I have always wanted to sell Wee Hur because it is not my kind of stocks (not an asset play or a dividend stock). I bought it years back when I was blindly following people in the forum without analyzing the fundamentals myself (I did not know how to do it then). The opportunity came this month when the price shot up too and I sold it on the same day as Sing Holdings for Singtel. Overall, we made an absolute loss of -16% and an annualized loss of -5.8%.

Croesus Retail Trust is another stock that got delisted this month as it was bought over at a premium to its NAV (similar to Saizen). Japan stocks are my lucky star. lol. Overall, we made an absolute +57.8% from it and an annualized return of +20.6% after holding for about 2.5 years.
BOUGHT
- Geo Energy (18,000 units) @ $0.27
- Capitaland Mall Trust (4,000 units) @ $2.02
- Capitaland Commercial Trust (2,000 units) @ $1.643
- Singtel (1,000 units) @ $3.68
In short, Geo Energy is a stock with crazy growth potential and many many years of coal to mine. lol. I will not even try to tell you how to value it because I know I cannot do a better job than these people:
ThumbTack Investor: https://thumbtackinvestor.wordpress.com/?s=geo+energy
SmallCapAsia: Will Geo Continue to Deliver?
Heartland Boy: Geo Energy: Initiation Report
SG investors.io: https://sginvestors.io/sgx/stock/re4-geo-energy-res/analyst-report
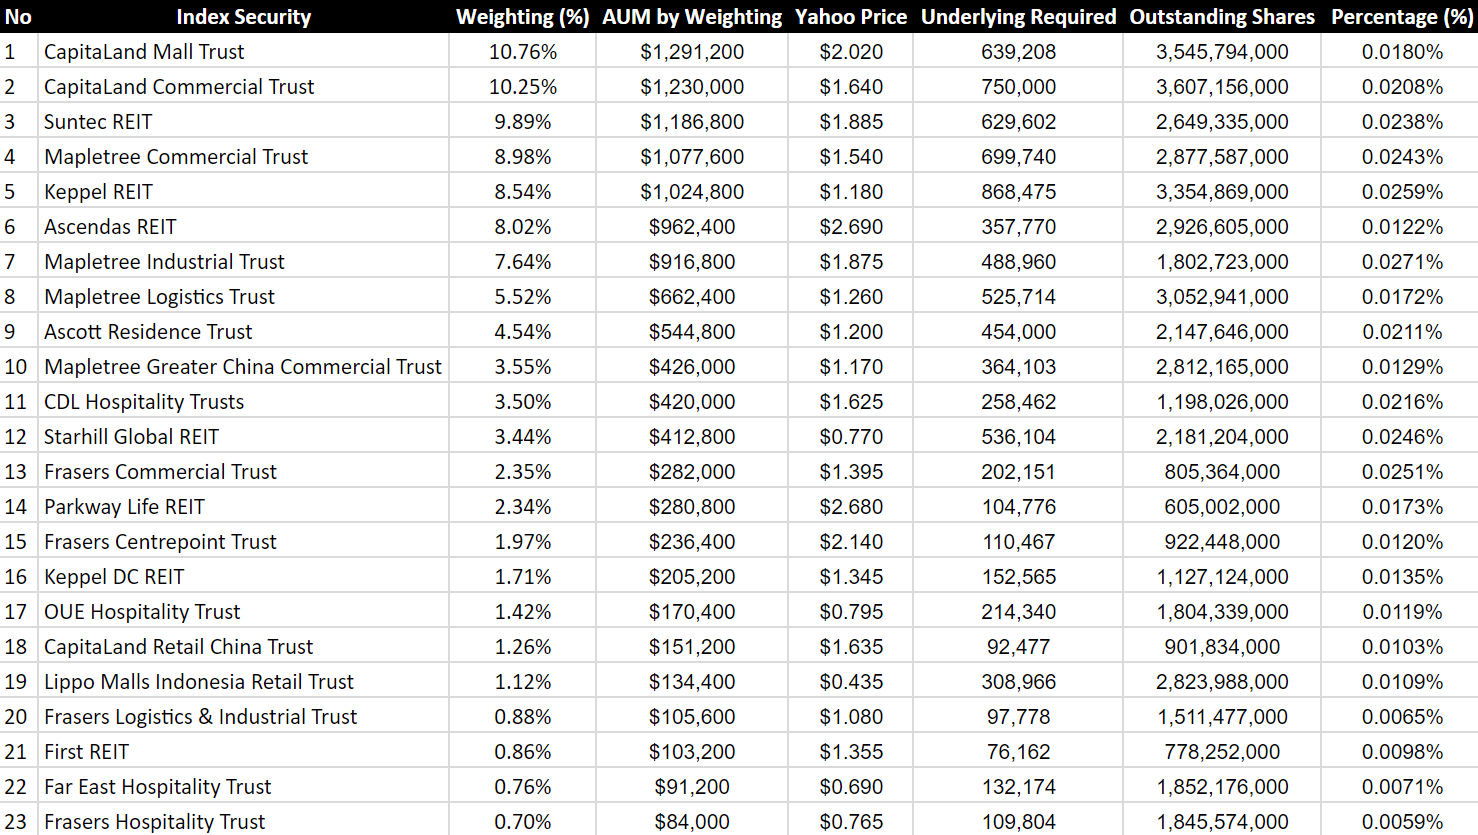
We were pretty interested in the Lion-Phillip S-REIT ETF but eventually decided to buy the underlying. Hence, we bought the top 2 REITs in the ETF. I made a mistake with Capitaland Commercial Trust Rights too. You can refer to these articles if you have yet to read them:
1. Mistake on Rights Issue - CapitaLand Commercial Trust
2. How ETFs Work - Using Lion-Phillip S-REIT ETF as an Example
3. 3rd REIT ETF - Lion-Phillip S-REIT ETF

As mentioned above, there was an opportunity to buy Singtel. Given the limited capital and the timely stop loss of Sing Holdings, I went on to liquidate Wee Hur and top up another $200+. Why Singtel?

The above information is extracted from SGX StockFacts sorted by market capitalization. This may come as a surprise to you but the market capitalization of Singtel is actually larger than our 3 banks! Too big to fail? Their business is so diversified that the 4th telco has limited impact. Furthermore, a 4+% dividend yield for a blue chip with the potential for capital growth is extremely attractive!
The total dividends collected this month is $1572.30. The breakdown is as follows:
Total dividends collected for 2017: $10,099.22
Average dividends per month for 2017: $841.60

Capital: $2,000
Current: $2,032.56 (IRR: 3.2%)
StashAway made a few changes to their interface and we love it! I will be publishing a separate article to discuss them. Stay tuned :)
StashAway Referral Link for Our Readers
Here you go: KPO and CZM Referral Link
Health - KPO Needs to Lose Weight
Date: 2017-11-02
Weight: 75.6 kg (Lost close to 8kg already!)
BMI: 25.2
Bought a new toy - Mi Smart Scale!
Do like any of the following for the latest update/post!
1. FB Page - KPO and CZM
2. Twitter - KPO and CZM
3. Click here to subscribe using email :)

There is a lot of activities this month!
SOLD
- Saizen REIT (8,900 units) @ $0.03223 (Delisted - P&L: $3,184.64)
- Sing Holdings (4,400 units) @ $0.47 (P&L: $321.04)
- Wee Hur (5,000 units) @ $0.285 (P&L: -$313.21)
- Croesus Retail Trust (6,801 units) @ $1.17 (Delisted - P&L: $3,339.89)

Saizen REIT was one of our first investment in REIT and we have been holding on to it for about 3 years. I was hoping the reverse takeover would happen but it did not. The huge loss in P&L is because when it got bought over, it distributed its capital in the form of dividends last year. Overall, we made an absolute +39.9% from it and an annualized return of +12.4%.

I was just blogging about Sing Holdings last month that it should trade nearer to its peers PB and it came faster than I expected! It was sold as the trailing stop loss I set got triggered. Fortunately, the price was near what I had in mind and there was a better opportunity (Singtel). Overall, we made an absolute +18.4% and an annualized return of +514.6% for holding 34 days. lol.

I have always wanted to sell Wee Hur because it is not my kind of stocks (not an asset play or a dividend stock). I bought it years back when I was blindly following people in the forum without analyzing the fundamentals myself (I did not know how to do it then). The opportunity came this month when the price shot up too and I sold it on the same day as Sing Holdings for Singtel. Overall, we made an absolute loss of -16% and an annualized loss of -5.8%.

Croesus Retail Trust is another stock that got delisted this month as it was bought over at a premium to its NAV (similar to Saizen). Japan stocks are my lucky star. lol. Overall, we made an absolute +57.8% from it and an annualized return of +20.6% after holding for about 2.5 years.
BOUGHT
- Geo Energy (18,000 units) @ $0.27
- Capitaland Mall Trust (4,000 units) @ $2.02
- Capitaland Commercial Trust (2,000 units) @ $1.643
- Singtel (1,000 units) @ $3.68
In short, Geo Energy is a stock with crazy growth potential and many many years of coal to mine. lol. I will not even try to tell you how to value it because I know I cannot do a better job than these people:
ThumbTack Investor: https://thumbtackinvestor.wordpress.com/?s=geo+energy
SmallCapAsia: Will Geo Continue to Deliver?
Heartland Boy: Geo Energy: Initiation Report
SG investors.io: https://sginvestors.io/sgx/stock/re4-geo-energy-res/analyst-report
We were pretty interested in the Lion-Phillip S-REIT ETF but eventually decided to buy the underlying. Hence, we bought the top 2 REITs in the ETF. I made a mistake with Capitaland Commercial Trust Rights too. You can refer to these articles if you have yet to read them:
1. Mistake on Rights Issue - CapitaLand Commercial Trust
2. How ETFs Work - Using Lion-Phillip S-REIT ETF as an Example
3. 3rd REIT ETF - Lion-Phillip S-REIT ETF

As mentioned above, there was an opportunity to buy Singtel. Given the limited capital and the timely stop loss of Sing Holdings, I went on to liquidate Wee Hur and top up another $200+. Why Singtel?

The above information is extracted from SGX StockFacts sorted by market capitalization. This may come as a surprise to you but the market capitalization of Singtel is actually larger than our 3 banks! Too big to fail? Their business is so diversified that the 4th telco has limited impact. Furthermore, a 4+% dividend yield for a blue chip with the potential for capital growth is extremely attractive!
The total dividends collected this month is $1572.30. The breakdown is as follows:
| Company | Symbol | ExDate | Shares | Total |
| First Real Estate Investment Trust | AW9U | 27-Oct-17 | 7,000 | $149.80 |
| CapitaLand Mall Trust | C38U | 26-Oct-17 | 7,000 | $194.60 |
| GuocoLand Ltd | F17 | 26-Oct-17 | 9,000 | $630.00 |
| Mapletree Greater China Commercial Trust | RW0U | 26-Oct-17 | 5,000 | $185.70 |
| Soilbuild Business Space REIT | SV3U | 20-Oct-17 | 30,000 | $412.20 |
Total dividends collected for 2017: $10,099.22
Average dividends per month for 2017: $841.60
StashAway

Capital: $2,000
Current: $2,032.56 (IRR: 3.2%)
StashAway made a few changes to their interface and we love it! I will be publishing a separate article to discuss them. Stay tuned :)
StashAway Referral Link for Our Readers
Here you go: KPO and CZM Referral Link
Health - KPO Needs to Lose Weight
Date: 2017-11-02
Weight: 75.6 kg (Lost close to 8kg already!)
BMI: 25.2
Bought a new toy - Mi Smart Scale!
Do like any of the following for the latest update/post!
1. FB Page - KPO and CZM
2. Twitter - KPO and CZM
3. Click here to subscribe using email :)