This is the second series of "Bleeding Stocks" where KPO will be looking at 老鼠屎 (rat shit) dragging down the overall performance of his portfolio. Do check out part 1 if you have not :)
Bleeding Stocks - QAF [Part 1]

QAF share price dropped because Q2 results were pretty bad. On the other hand, Raffles Medical Q2 results were much better as compared to QAF - Raffles Medical Group's Q2 profits marginally higher. Let's take a closer look at the financials.

There is almost no change but the same cannot be said for its share price. Based on its last closed price on 2017-08-11 of $1.13. It has fallen by 25.4% as compared to the price one year ago ($1.515 on 2016-08-11). What has changed to warrant such a huge drop? No idea. Your guess is as good as mine - a few analysts sell reports + not meeting its growth expectation?

Similarly, I compiled the last 5 years of financial results and you can refer to it here. Raffles Medical has been growing at a steady rate with increasing NAV and operating cash flow over the years. There was a share split (3 for 1) in May 2016 hence the numbers had to be adjusted slightly. Based on the data, it seems that Raffles Medical has been trading at a average PE of 31.7 and PB of 4.109. Assuming that EPS and NAV remains constant (2016 EPS $0.040 and NAV of $0.395), the average PE of 31.7 will translate to $1.268 and PB of 4.109 will be $1.624.
Some of you may think that PE of 31 is way too high but if you compare it against the industry - Healthcare Providers and Services, you will see that it is a premium one has to pay for defensive healthcare related stocks.

Based on both shareinvestor.com and SGX StockFacts, Raffles Medical currently trades at a PE of 28.485 is which is much lower than the industry average. Interestingly, Raffles Medical is the second largest company with a market capitalization of $2,001 billions. The largest one being IHH Healthcare Berhad with $15,438 billions trading at a PE of 75.806!

This is a summary of what to expect in the future and how Raffles Medical will continue to grow according to the latest Q2 report:
- RafflesMedical expanded its network of clinics in 2017 by opening a new clinic at Hillion Mall in Q2 2017
- Northpoint will also be re-opened in September 2017. Existing clinics at Asia Square, Clementi and Nex have been relocated or refreshed in Q2 2017
- RafflesHospital Extension’s completion and opening in Q4 2017
- Changi Airport Terminal 4, Transit 4, and two new in-house clinics in Dover and Tampines respectively, are scheduled to open in Q3 2017
- RafflesHospital’s Emergency Care Collaboration with the Ministry of Health (MOH) was extended in June 2017 for another 5 years, allowing SCDF ambulances to continue to bring patients to RafflesHospital for subsidised care
- Construction of RafflesHospital Chongqing (operational by second half 2018) and RafflesHospital Shanghai (operational by second half 2019) is progressing according to plan

At the end of the day, KPO finding Raffles Medical undervalued does not mean anything. However, when you have the founder/CEO Dr. Choon Yong Loo increasing his shares at $1.44 last year (2016-06-29) and at $1.26 this year (2017-06-30) together with a major fund buying it at $1.21 on 2017-08-07. It probably means something. lol.

Since this is the 2nd series, let me end off with 2 charts. Raffles Medical has been on a down trend since last year. The current support is at $1.10 and $1.09 while resistance is at $1.17 and $1.21. Extremely bearish as price is still trading below all the moving averages.

However, do you see a tiny hammer supported by significant volume? The RSI (Relative Strength Index) seems to indicate that the stock has been oversold or is currently in a undervalued condition too.
With the above fundamental analysis, KPO queued for 6,000 units at $1.10 yesterday (2017-08-11) and my orders were filled :) This brings my average price to $1.308 and loss to -12.92%. Patched my wound in 1 day or would it be a falling knife? Only time will tell. lol.

Bleeding Stocks - QAF [Part 1]

QAF share price dropped because Q2 results were pretty bad. On the other hand, Raffles Medical Q2 results were much better as compared to QAF - Raffles Medical Group's Q2 profits marginally higher. Let's take a closer look at the financials.

There is almost no change but the same cannot be said for its share price. Based on its last closed price on 2017-08-11 of $1.13. It has fallen by 25.4% as compared to the price one year ago ($1.515 on 2016-08-11). What has changed to warrant such a huge drop? No idea. Your guess is as good as mine - a few analysts sell reports + not meeting its growth expectation?

Similarly, I compiled the last 5 years of financial results and you can refer to it here. Raffles Medical has been growing at a steady rate with increasing NAV and operating cash flow over the years. There was a share split (3 for 1) in May 2016 hence the numbers had to be adjusted slightly. Based on the data, it seems that Raffles Medical has been trading at a average PE of 31.7 and PB of 4.109. Assuming that EPS and NAV remains constant (2016 EPS $0.040 and NAV of $0.395), the average PE of 31.7 will translate to $1.268 and PB of 4.109 will be $1.624.
Some of you may think that PE of 31 is way too high but if you compare it against the industry - Healthcare Providers and Services, you will see that it is a premium one has to pay for defensive healthcare related stocks.

Based on both shareinvestor.com and SGX StockFacts, Raffles Medical currently trades at a PE of 28.485 is which is much lower than the industry average. Interestingly, Raffles Medical is the second largest company with a market capitalization of $2,001 billions. The largest one being IHH Healthcare Berhad with $15,438 billions trading at a PE of 75.806!

This is a summary of what to expect in the future and how Raffles Medical will continue to grow according to the latest Q2 report:
- RafflesMedical expanded its network of clinics in 2017 by opening a new clinic at Hillion Mall in Q2 2017
- Northpoint will also be re-opened in September 2017. Existing clinics at Asia Square, Clementi and Nex have been relocated or refreshed in Q2 2017
- RafflesHospital Extension’s completion and opening in Q4 2017
- Changi Airport Terminal 4, Transit 4, and two new in-house clinics in Dover and Tampines respectively, are scheduled to open in Q3 2017
- RafflesHospital’s Emergency Care Collaboration with the Ministry of Health (MOH) was extended in June 2017 for another 5 years, allowing SCDF ambulances to continue to bring patients to RafflesHospital for subsidised care
- Construction of RafflesHospital Chongqing (operational by second half 2018) and RafflesHospital Shanghai (operational by second half 2019) is progressing according to plan
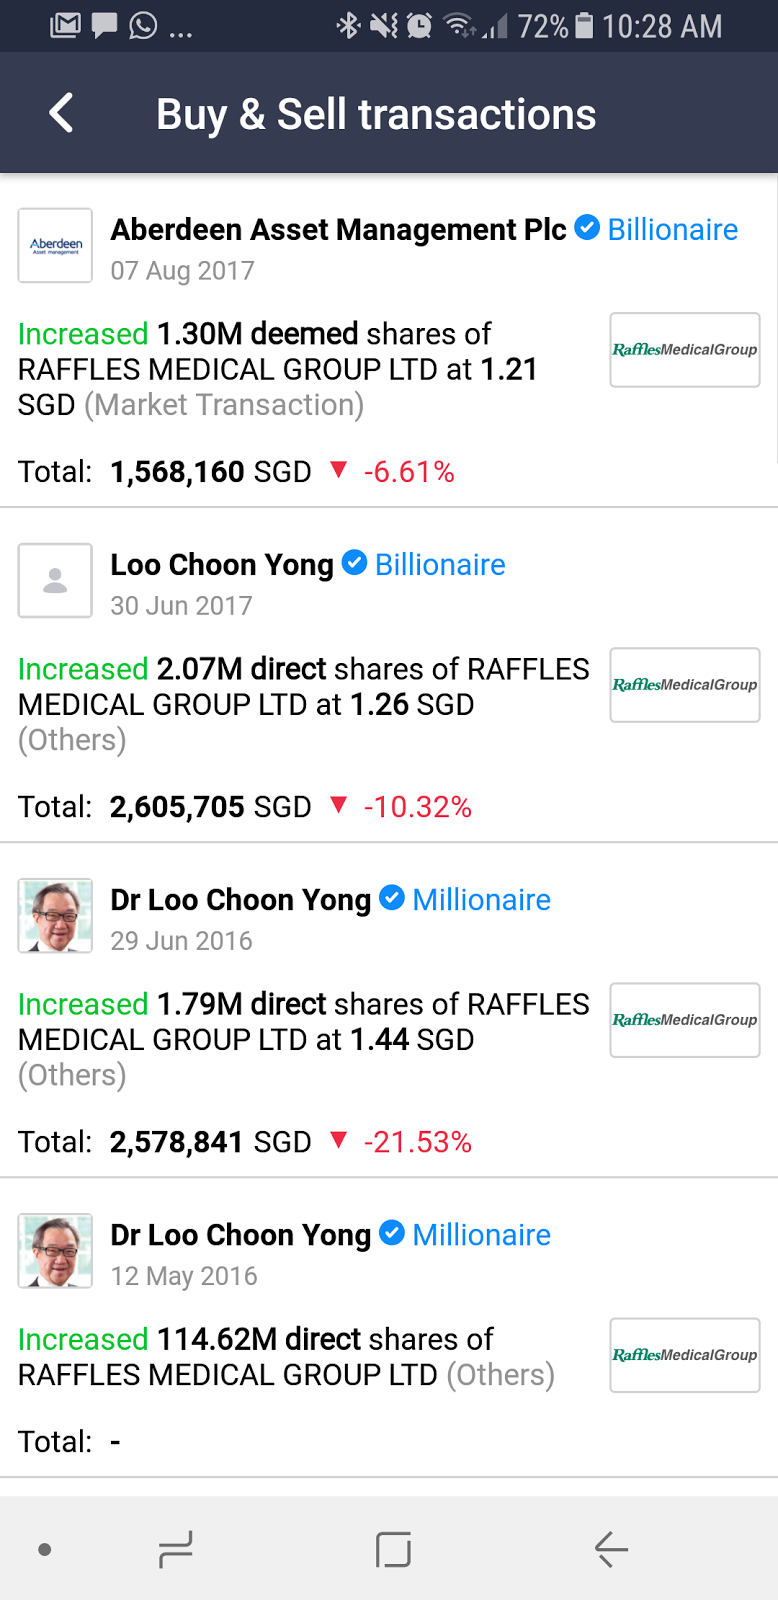
At the end of the day, KPO finding Raffles Medical undervalued does not mean anything. However, when you have the founder/CEO Dr. Choon Yong Loo increasing his shares at $1.44 last year (2016-06-29) and at $1.26 this year (2017-06-30) together with a major fund buying it at $1.21 on 2017-08-07. It probably means something. lol.

Since this is the 2nd series, let me end off with 2 charts. Raffles Medical has been on a down trend since last year. The current support is at $1.10 and $1.09 while resistance is at $1.17 and $1.21. Extremely bearish as price is still trading below all the moving averages.

However, do you see a tiny hammer supported by significant volume? The RSI (Relative Strength Index) seems to indicate that the stock has been oversold or is currently in a undervalued condition too.
With the above fundamental analysis, KPO queued for 6,000 units at $1.10 yesterday (2017-08-11) and my orders were filled :) This brings my average price to $1.308 and loss to -12.92%. Patched my wound in 1 day or would it be a falling knife? Only time will tell. lol.

Thanks for reading! Hope you all enjoyed it. Stay tuned for Part 3! (May not be anytime soon since I sort of mentally write off that investment. lol.)


