$$$ KPO and CZM $$$: IPO
Showing posts with label IPO. Show all posts

Sunday, May 5, 2019

IPO - ARA US Hospitality Trust VS Eagle Hospitality Trust

I usually don't look at stocks/REITs in overseas currency but given how the yield of the local REITs have been compressed (~4/5%+). I took a quick look at these 2 US hospitality trust.

ARA US Hospitality Trust
There are 38 hotels/properties, 4,950 rooms by Hyatt (Hyatt Place and Hyatt House).

Offering Price: US$0.88
NAV: US$0.86
PB: 1.02


Estimated/Forecast Dividend Yield for 2019: 8.0%
Estimated/Forecast Dividend Yield for 2020: 8.2%
Gearing: 35.9%

Closing date and time for the Singapore Public Offer: 7 May 2019, 12pm


The revenue was lower for FY2016 due to the disruptions from renovations while the decrease in FY2018 was due to the following: 1) disruptions in operations from the marketing sale process of the Initial Portfolio by the previous owner and 2) supply increases in certain markets that diluted demand temporarily.


Naturally, we will see the same trend in the NPI.


RevPAR of around US$90+.

Eagle Hospitality Trust
There are 18 hotels/properties, 5,420 rooms across different brands - IHG, Marriot, Hilton, and Independent.

Offering Price: US$0.81 or US$0.82
NAV: US$0.89
PB: 0.91 - 0.92


Estimated/Forecast Dividend Yield for 2019: 7.9% to 8.0%
Estimated/Forecast Dividend Yield for 2020: 8.1% to 8.2%
Gearing: 38.0%


Increasing Revenue, NPI and distribution income year on year.


RevPAR of around US$90+ too. They are expecting RevPAR to improve due to newly renovated or refurbished hotels and rooms or improved revenue management. Certain hotels are expected to generate increased room revenue from contracts with corporates or government agencies. Room revenue at Holiday Inn Resort Orlando Suites – Waterpark is also expected to improve from potential partnerships with certain brands to improve occupancy rate in the off-peak season

KPO's Thoughts
I prefer Eagle Hospitality Trust over ARA US Hospitality Trust for a few reasons. The hotels listed by Eagle Hospitality Trust are by different brands and are of higher "quality" as compared to ARA US Hospitality Trust. People that stay in the above hotels are probably better off and would not mind paying more for various reasons or have some form of hotel loyalty/membership. The problem with ARA US Hospitality Trust is that it will probably only attract Hyatt members. Otherwise, for that price, Airbnb might be a better option?

In addition, the above numbers speak for itself. I am not sure if ARA US Hospitality Trust deserves to be trading at PB 1... For all we know, it may even be snatched up by yield hungry investor to sustain the above book valuation. No crystal ball to tell you what will happen exactly.


Last but not least, do take note of the exchange rate risk. You may be looking at capital gain for your investment but in actual fact, the return could be "countered" by the exchange rate. Having said that, it can also work for you and give the return a boost.

We will be sitting out for ARA US Hospitality Trust IPO. All the best to those that are applying for them! Huat ah!

You can find their prospectus here:
ARA US Hospitality Trust
Eagle Hospitality Trust

Do like any of the following for the latest update/post!
1. FB Page - KPO and CZM
2. Twitter - KPO and CZM
3. Click here to subscribe using email :)
4. Instagram - KPO_and_CZM (Did you see those delicious food photos to the right --> Unfortunately, you can't see it on mobile.)

Monday, May 14, 2018

IPO - Hyphens Pharma International Limited

It has been a while since there was an IPO that interest us me. CZM is not joining because she has never heard of this company or their products. Neither have I but I am just a number guy. You can find the prospectus here.

Hyphens Pharma International Limited is a pharmaceuticals/medical company with the following 3 core businesses:
- Specialty pharma principals (53.6% of 2017 total revenue)
- Proprietary brands (11.4% of 2017 total revenue)
- Medical hypermart and digital (35.0% of 2017 total revenue)

There will be 29,600,000 Invitation Shares with 3,000,000 Public Offer Shares and 26,600,000 Placement Shares at S$0.26. The closing date will be 16 May 2018 at 12 pm and it will start trading on 18 May 2018 at 9 am.


From what I can understand, they sell/distribute drugs:
- Specialty pharma principals = selling/distributing other companies' drugs
- Proprietary brands = selling their own drugs + patents (Ceradan and TDF)
- Medical hypermart and digital = selling drugs online


With an IPO price of $0.26 and an EPS of 2.0 cents, the stock will be trading/listing at a PE of 13. My eyes blink $_$ when I saw this as healthcare related stocks generally trade at a huge premium!


Their dividend policy states that they intend to distribute at least 30% of net profits. Assuming EPS remains constant for 2018, that will translate to a dividend yield of (0.02 x 0.3) / 0.26 ~ 2.31%. What I dislike is that they have already paid themselves handsomely before the IPO >.<


The valuation is so cheap that even with an average PE of 15 (not industry average), the IPO looks like a bao jiak (sure win) using my IPO Hit and Run Calculator (sell on day 1 with the assumption that it trades at the expected average PE). Even Mr. IPO gave a 3 chill ratings which mean "This IPO is hot. Your $2 is probably going to buy you a romantic dinner for 2 with a bottle of red wine included. Likely opening price: More than 20% upside". You can find his analysis here.

I applied 40,000 shares for placement but was not allocated any. My broker asked me to try my luck at ATM -.- Pretty hot? Huat ah!

Update on 17th May 2018 - KPO has no luck in IPO


Do like any of the following for the latest update/post!
1. FB Page - KPO and CZM
2. Twitter - KPO and CZM
3. Click here to subscribe using email :)
4. Instagram - KPO_and_CZM (Did you see those delicious food photos to the right -->)

Wednesday, November 29, 2017

What's Harder than BTO? IPO

I always thought applying for a BTO was hard, until I try IPOs! $6 for 3 tries but did not get any!


Even though we did not get any shares from the public tranche, we decided to purchase MindChamps from the market and hold it long term because we believe that parents are willing to spend money on their children to give them the best. So I place an order before the market open at $0.84 but did not get any (not sure why). I continued to chase (kept modifying the order) the price and finally got in at $0.875 for 5000 units. MindChamps went on to close at $0.92!

On Monday (27th November), MindChamps closes at $0.96 which means it was trading at a PE of 43x! However, the next day, MOE releases a news -
MOE kindergarten kids get priority admission to co-located primary schools from next year which would definitely have an impact on private preschool including MindChamps. Not sure if MOE is trolling or already give face to MindChamps by releasing the news at this time. lol. The price went on to close at $0.915.

Appeal of MOE Kindergartens will shoot up, parents say. Parents simply want the best for their children and this news is a big deal! We decided to put a stop loss at $0.90 and guess what? We got kicked out today with a little bit of profit $104.11 (+2.4%) and an annualized return of +454.5%! So much for holding long term. Hahaha.


Should we chase No Signboard tomorrow? Probably not. Since the public tranche is 268.6 times subscribed, the public demand should be huge! Huat to those that got it!

Sunday, November 19, 2017

IPO Hit and Run Calculator

KPO is sharing more spreadsheet! Hahahaha.

We have a few IPO upcoming and the latest one is RE&S Holdings Limited (closes on tomorrow/19th November 12pm) followed closely by MindChamps (closes on 22 November 12pm).

This post is not about my analysis of the company. You can refer to these analyses:
- Singapore IPOs: RE&S Holdings Limited
- sginvestors.io: Phillip Securities IPO Note
- Singapore IPOs: MindCamps Preschool Limited

I did a 3 years analysis a few months back on IPOs - Will IPO Make Money - IPO Analysis for the Last 3 Years. Do take a look if you have not :) I jokingly concluded that we should participate in all the IPOs and sell on its opening day! While I was reading Mr. IPO's summary on RE&S Holdings, he mentioned that this IPO will be a hit and run and I thought of coming up with this spreadsheet.

A quick way to tell if a company is trading at fair value is to compare its PE against that of its peers. In the above analysis, we can be sure that RE&S Holdings is trading below the industry average PE. Do note PE comparison is a quick way to compare stocks, not the best way. Is there even a best way? lol.


Using RE&S Holdings as an example, the following highlighted fields can be modified/configured with the relevant numbers. Based on the budget/cash you have, it will automatically compute the number of units that can be applied. One can apply for IPO either through the public tranche (ATM or ibanking) with a $2 application fee or through placement where the brokerage fee is at 1% with 7% GST.


Assuming that we were allocated X number of units and we sell the stock at around industry PE which is $0.255. Regardless of the number of units allocated, we will definitely profit from it including all the fees!


However, if we were to sell the stock slightly higher than IPO price at $0.225, depending on the number of units allocated, we may/may not lose money after deducting the initial cost and the commission from selling the stock. This spreadsheet will also be helpful in determining a trailing stop loss for your IPO stock.

Google spreadsheet can be accessed here - IPO Hit and Run Calculator. Have fun!

On a side note, we will be applying for 101,000 units of RE&S Holdings Limited. Huat ah!

Do like any of the following for the latest update/post!
1. FB Page - KPO and CZM
2. Twitter - KPO and CZM
3. Click here to subscribe using email :)
4. Instagram - KPO_and_CZM (Did you see those delicious food photos to the right -->)

Saturday, September 30, 2017

3rd REIT ETF - Lion-Phillip S-REIT ETF

[This is outdated due to Singapore Budget 2018 - Take a look at this post (New Singapore Budget, New REIT Strategy!) instead ]

KPO and CZM are back from our long 2 weeks holiday and we missed the APAC Realty IPO! I can only console ourselves that we have not been very lucky with IPOs so we will most likely waste the $2...

On the bright side, a 3rd REIT ETF - Lion-Phillip S-REIT ETF will be listed on SGX. The main difference is that the REITs in the ETF are all from SGX. The ETF attempts to replicate the Morningstar Singapore REIT Yield Focus Index (click on "Equity" follow by "Dividend"). You can refer to the prospectus in MAS site for more information too.

Since this is not an IPO, one will not be able to apply through ATM or I-banking. It was stated in the prospectus that the issue price of each unit during the Initial Offer Period is S$1.000 and it will be listed on 30th October 2017. However, one has to apply for a minimum of 50,000 units through one of the participating dealers (Phillip Securities Pte Ltd, DBS Vickers Securities (Singapore) Pte Ltd, Commerzbank AG and UOB Kay Hian Pte Ltd) and the application fee is $450 instead of $2 >.<


The ETF comprises of 23 SGX REITs with different weighting. I extracted the dividend yield of each REIT according to reitdata.com and compute the estimated dividend yield based on their weighting to obtain an estimated dividend yield for the ETF - 5.82% 4.81% (after deducting off 17% corporate income tax). The ETF aims to distribute dividends semi-annually (which are not guaranteed).


The expense ratio for the ETF is currently unknown but the information on the various fees and charges were provided (at least 0.55%?).

We are definitely interested in this but since we cannot afford to apply for 50,000 units, we will probably buy it from the secondary market. Let's see how it goes!

Update on 01 October 2017:
As pointed out by ziyang and others in one of the FB group discussion, there are corporate income tax rate of 17% on the dividends for the ETF which will reduce the overall return significantly! We will probably give this a miss instead!

Update on 03 October 2017:
Confirm that my analysis is correct, after tax withholding/corporate income tax, the dividend yield would be around a high 4%+!


Health - KPO Needs to Lose Weight
Date: 2017-09-30
Weight: 80.1 kg (put on more weight after the vacation!)
BMI: 26.7 

Friday, July 14, 2017

Just Another Netlink Trust IPO Analysis

This is one of the biggest IPO in recent years and by now there are many articles written about it. You can refer to these articles instead (if you have not), they definitely write and analyze better than me:

1. One cannot make a decision on IPO without Mr. IPO's chili ratings - Netlink NBN Trust (Update)
4. SG Budget Babe - IPO Analysis: NetLink Trust

So the question is will KPO go for the IPO? Finally took some time to look at the prospectus and highlight sheet. I will be ignoring those forecast/projected numbers for 2018 and 2019 as they will always paint a bright and happy future. Who will forecast their business to lose money?? lol.

We know that the offer price is at $0.81 with total net assets of $3,070,815,000. Assuming the over-allocation option is exercised in full (3,021,456,001 units), the NAV will be $1.02. If there is no over-allocation, there will be 2,898,000,001 units instead and the NAV will be $1.06. That is about 20% discount, what a good deal?!


Unfortunately, if you were to look at its balance sheets, you can see $1,009,569,000 of intangible assets. To put it in simple terms, that is $1 billion of nothing. lol. KPO is very practical and does not like intangible assets. Digging deeper into the prospectus, one will be able to find the breakdown for the intangible assets which consists of 2 items - Licence and Goodwill.


Such a high goodwill?! Let me provide you a proper definition taken from Investopedia - Goodwill is an intangible asset that arises as a result of the acquisition of one company by another for a premium value. The value of a company’s brand name, solid customer base, good customer relations, good employee relations and any patents or proprietary technology represent goodwill.

Do read these 3 articles for more information:
- Investopedia - Intangible Asset
- Investopedia - Goodwill
- Investopedia - Goodwill vs Other Intangible Assets: What's the Difference?


Personally, I like to be more conservative in calculating the NAV. Hence, removing the goodwill from the total net asset will result in the NAV dropping significantly to $0.79 or $0.75 if the over-allocation option is exercised. If they were to offer at the higher end of the indicative range ($0.80 to $0.93), I would not have participated in the IPO. It seems that the biggest winner is probably Singtel and the banks (bookrunners/underwriters).

With the most recent Yventures IPO, the offer price was at $0.22 and it closed at $0.255. So far 2017 continues to be a great year for IPO and my analysis still holds true! Do take a look if you have not - Will IPO Make Money - IPO Analysis for the Last 3 Years


Paying a little premium for a business with increasing positive operating cash flow year on year, operating in a monopoly market with a dividend yield of around 5.73% seems reasonable. KPO shall apply small small for 20,000 units and hold for 23 years.

Huat ah!

Saturday, July 8, 2017

Will IPO Make Money - IPO Analysis for the Last 3 Years

KPO recently met up with a group of friends. We are all working for different companies now and 1 of them works in SGX. I laughed at him claiming that he is one of the directors for those companies cause I have seen him appearing at IPO events, taking photos, etc on the SGX FB page - SGX | My Gateway. He then made an interesting comment stating that all IPO will make money (sell on the opening day). How true is it?

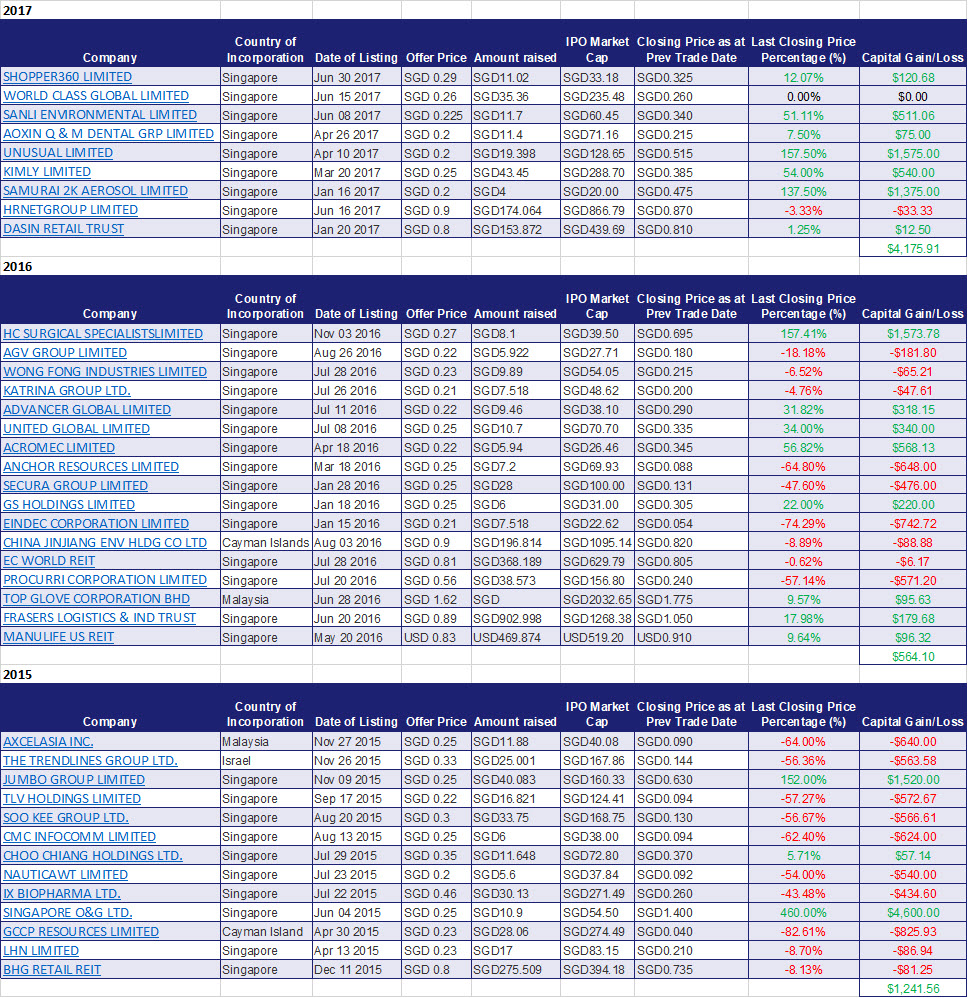
KPO went to SGX website and found a page where past performances of the IPOs are being tracked! Unfortunately, SGX only provides data for the last 3 years, hence that limits my analysis (it would have been great if we can see how did IPOs perform during the financial crisis). I spent some time to clean up the data and present to you the following tables and conclusion which I found it to be quite interesting:


At one glance you can see more green color which represents a positive return if you were to sell at/near the closing price. Assuming if I were to invest $1,000 in each IPO and sell it on the first day, I would indeed be sitting on a huge profit!


That is a simple calculation of return for 1 day, the annualized return will be ridiculous! The total return is a +20.25% gain ($7,895.57 from $39,000). 2017 has a much higher return because it has lesser number of IPOs year till date. Furthermore, we are in a bull market where 100% of the IPOs closed higher than offer price! Will the same happen for the upcoming Netlink Trust? xD

Now let's assume that I invest in $1,000 in each IPO, forget about them and hold until today, what would be my return? I should make more money right??


OMG! This kind of results will get caned by my mother one! So many failed subjects, all red red >.<


The total return is +15.38% ($5,981.57 from $39,000) after 3 years. The above calculations are simplified as dividends are not taken into account. If you looked carefully, the returns are positive due to exceptional huge return by a few stocks.

For example:
2015 IPOs - Jumbo returns 152% while Singapore O&G return 460% till date!
2016 IPOs - Acromec returns 57% and HC Surgical returns 57%!

Moral of the article: Buy/Participate in all the IPOs and sell on its opening day! Trust the guy working in SGX! Just kidding, do note that past performance is not a good indication of how the future performance will be. The above strategy will only work IF you can participate in all IPO but the chances of getting it seem so low that you have a higher chance applying for BTO.

The pictures might be quite small and if you are interested in looking at the raw data. You can refer to this link - IPO Analysis. (The formulas are in my Excel spreadsheet but sharing that may reveal my identity so please make do with the google spreadsheet. lol)

Hope you guys enjoy this! On a side note, I have changed the blog name and URL to include CZM since she *might* be coming back.

Saturday, June 10, 2017

Portfolio Update - May 2017

It has been 6 months since we I started blogging and unknowingly, the blog has crossed another milestone, it has more than >10k views! Thank you to all the readers out there and I hope that you guys enjoyed whatever stuffs we are sharing. CZM sort of lost interest cause she says this blog is not making money. We applied for Google AdSense but was rejected. lol. Let's see if she ever returns...

Our portfolio grew by 3.85% this month mainly due to capital injection.


We saw some weakness in the price of Capitaland when it fell from a high of $3.78 to $3.46 and that was when we decided to pull the trigger and add more Capitaland shares to our portfolio. It has a NAV of $4.16 and a higher RNAV which also means we are buying at a discount of at least 20%. While waiting patiently for it to hit NAV, it has a dividend yield of 2.78%. Most importantly, it has strong kao shan (靠山 - translate to supported by mountain. lol).

SGX StockFacts - Ownershiper

I was looking for new stocks to buy as the price of most developer and REITs stocks have rise significantly, some even reaching 52 weeks high. Furthermore, CZM always says I need to diversify our portfolio, so I decided to buy some bread! When you look at its PE ratio, it is pretty undervalued when compared to its peers (6 vs 19-26).

ShareInvestor

Looking at its operating cash flow, we can see that it is a rather profitable business too! QAF has also been consistently paying a $0.05 per share of dividend every year (around 3.75% dividend yield).

SGX StockFacts - Financials

We also applied for Sanli IPO (101,000 units) but was not allocated any units. My friend applied 168,000 units cause he says lucky number maybe higher chance - he was not allocated if you are thinking of trying next time. IPO seems to be as hard as applying for BTO or maybe harder?! We got our BTO during our third try, let's see if IPO is faster. (Technically, we can IPO another 13 times since the application fee for BTO is $10 each. lol)

BOUGHT
- QAF (3,000 units) @ $1.33
- CapitaLand (2,000 units) @ $3.48 [Total units: 4,000 units]

The total dividends collected this month is $2014.95. The breakdown is as follows:

Company Symbol ExDate Shares Total
CapitaLand Ltd C31 02-May-17 2,000 $200.00
Wee Hur Holdings Ltd E3B 02-May-17 5,000 $15.00
Mapletree Greater China Commercial Trust RW0U 03-May-17 5,000 $186.55
Starhill Global Real Estate Investment Trust P40U 04-May-17 12,000 $141.60
Chip Eng Seng Corporation Ltd C29 05-May-17 8,000 $320.00
Raffles Medical Group Ltd BSL 08-May-17 4,000 $120.00
Hong Fok Corporation Ltd H30 08-May-17 16,500 $165.00
Lippo Malls Indonesia Retail Trust D5IU 09-May-17 4,000 $35.60
Frasers Logistics & Industrial Trust BUOU 12-May-17 8,000 $279.20
Sheng Siong Group Ltd OV8 12-May-17 14,000 $259.00
OUE Ltd LJ3 12-May-17 10,000 $200.00
Far East Hospitality Trust Q5T 18-May-17 10,000 $93.00

Total dividends collected for 2017: $4785.96
Average dividends per month for 2017: $398.83

Monday, March 13, 2017

KPO's Virgin IPO (Kimly) After 4 Years!

I have never participated in any IPO after investing for 3/4 years. The reason is because one cannot do that with SCB and I have been trying to resist all temptations in order to accumulate all my investment in one account. I no longer need to do that as I have achieved that goal last month!

I am sure by now everyone is familiar with our (SGX) very first kopi-tiam (it means coffee shop in Hokkien, not to be confused with the food court Kopitiam) IPO - Kimly Limited. I would love to invest in Kopitiam and Koufu too whenever I see those crowd during meals time...

This is beyond my comfort zone as I can no longer value it simply using its NAV, CNAV, PB, etc. and to participate in this IPO would mean that I am not buying this at a discount/safety margin. At its IPO price, the PB (Price to Book ratio) is 5.51 and the NAV is only 4.56 cents >.<"" However, I do like the fact that it is paying dividends. Assuming if its payout ratio is at 50%, I will be able to get 4% dividend yield :)


For a more comprehensive analysis on Kimly, do refer to the masters/shi-fu below:
- Singapore IPOs: Kimly Limited
- Forever Financial Freedom: Kimly Limited IPO - Should You Be Getting This?
- 10% Per Annum: Kimly IPO - Exciting Stuff?

I went through Singapore IPOs past analysis on F&B related companies:
1. Katrina Group Ltd (July 2016)
- IPO price @ $0.21, EPS 1.51 cents, dividend yield ~4% (60% payout ratio) but no public tranche
- Closed $0.34 on first day (64% gain), current market price $0.21. lol

2. Jumbo Group (November 2015)
- IPO price @ $0.25, EPS 2.7 cents, dividend yield ~2.5% (30% payout ratio) with 2 million public tranche
- Closed $0.34 on first day (36% gain), current market price $0.68 O_O
- The 2 million public tranche was > 300x subscribed!! Investors who apply for 50 lots will get a 3:99 chance and be allocated 8,000 shares.
This time round Kimly has 3.8 million public tranche. Assuming the same number of people are interested, it would be at least > 150x subscribed but there will probably be more people around now?? So 50 lots will get 16,000 shares or 4000 shares?? KPO maths not good, CZM say I cannot teach our baby maths in the future. Anyway, KPO has decided to participate and made his virgin IPO application. Is there such a thing as beginner's luck for IPO?

Good luck to myself and all the applicants! Huat ah!